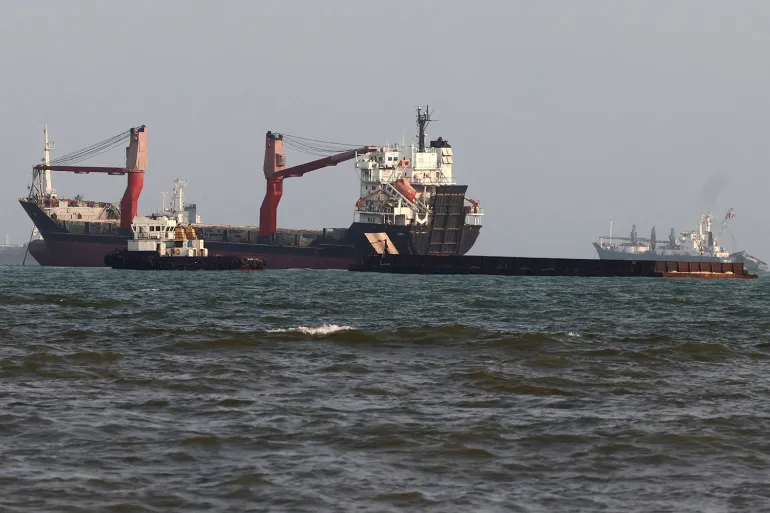
Total Hormuz Clearance, Kpler’s measure combining Strait of Hormuz transits and Gulf of Oman ship-to-ship net exports, is about 30% below its pre-war level. Tanker strikes have reached their highest weekly count this year, and freight rates have hit records, according to a Kpler media briefing dated 12 October 2026.
Kpler’s flow data, current to 10 October, shows confirmed Total Hormuz Clearance at 4,504 thousand barrels per day (kbd) that day, down from 7,539 kbd on 9 October and 24,140 kbd on 8 October. The 7-day average of 11,922 kbd compares with a pre-war baseline of 17,132 kbd. Strait transits alone averaged 10,538 kbd over the same period.
Kpler cautioned that the latest readings are preliminary and have typically settled 1.5 to 2 times higher as confirmations land. All figures cover oil only (crude, clean and dirty products, and chemicals/bio), excluding NGLs and LNG.
Bypass routes soften the blow
Adding Gulf of Oman terminals and the Red Sea lifts the regional 7-day average to 20,166 kbd, about 13% below its baseline.
Kpler Insight reported that Fujairah crude loadings reached a record 2.62 million barrels per day (mbd) in September. Net exports, which exclude crude delivered by tanker, also set a record at 2.38 mbd, above the 1.5 to 1.8 mbd commonly cited for the ADCOP pipeline. Kpler said the figures show how far bypass routes are offsetting the strait. It said the surplus most likely came from newly operational 42 million barrel underground storage.
About 11.4 million barrels were drawn from storage in September, leaving an estimated 30.6 million barrels, or roughly 80 days at that pace. The West-East Pipeline, due in 2027, would lift pipeline capacity to Fujairah to around 3.3 mbd.
Tanker strikes at a yearly high
Kpler Insight reported that 10 tankers were struck in the strait between 28 September and 4 October, the highest weekly count this year, with a further strike on 5 October. Kpler data show at least four confirmed incidents involving Aframax tankers since 29 September. The briefing does not attribute the attacks.
Tanker crossings of the strait averaged 12 a day over the past week, against 50 before the war. Daily crossings were 18 on 7 October, 17 on 8 October, 8 on 9 October and 1 on 10 October. The most recent day, with no entries and one exit, is preliminary and likely to be revised up.
Kpler Insight reads the heightened risk as a bargaining tool for owners seeking higher rates rather than a decisive deterrent. Kpler expects transits to resume in the coming week, because risk is being priced into freight rather than halting flows.
Freight rates at records
Middle East to China VLCC rates reached a record $38.47 per barrel, Kpler Insight reported, with more than 70 VLCCs now working in shuttle trades, including more ship-to-ship activity off West Coast India. Kpler expects dirty tanker rates to stay elevated through the fourth quarter.
Kpler Insight also said Iran has not loaded a crude cargo since late August under the US blockade, and that Chinese teapot refiners are paying up to $18 per barrel over Brent for Basrah crude, which points to missing Iranian barrels. Iranian-origin transits are excluded from the strait figures.
Red Sea volumes above baseline, but threats persist
Red Sea volumes averaged 3,741 kbd over seven days, above a pre-war baseline of 2,803 kbd. Kpler said the latest reading is preliminary because the figures include cargo with no confirmed load terminal.
Kpler Insight reported that satellite imagery from 4 October showed two tankers loading at Yanbu, with all three berths at Muajjiz occupied. Asian buyers are resuming Sumed bypass routes to lift Saudi crude without crossing the southern Red Sea.
Risk remains elevated. Kpler Insight reported on 5 October that six ballistic missiles aimed at Taif and Yanbu had been intercepted, with no damage to Aramco installations. On 6 October it reported that a Houthi official had warned Saudi oil facilities and the Bab el-Mandeb strait could be targeted.
According to Kpler Insight, a drone attack on 11 September forced the East-West Pipeline offline. Flows have since recovered to 5.8 mbd, but given the threat of further attacks Kpler expects Saudi crude supply to average around 9 mbd in October. Confirmed loadings at Yanbu and Muajjiz reached 42 million barrels between 17 September and 4 October.
Refined products trail crude
Gulf clean product loadings eased to 2.5 mbd from 3 mbd earlier in September, still around 50% below pre-war levels. Kpler Insight explained that crude is a single large stream, while products need six or seven grades, segregated tanks and vessel space to move in step, so one missed ship-to-ship transfer window can delay a whole refinery loading schedule.
Middle East refinery runs were about 7.4 mbd in September, roughly 2.1 mbd below a year earlier. Saudi runs fell about 100 kbd month on month to around 2.1 mbd, with East-West Pipeline damage and the Jizan outage, which has lasted since late July, both weighing. Kpler expects Jizan to restart from mid-November and regional runs to recover to about 8.1 mbd in the fourth quarter, depending on tanker traffic through Hormuz.
In the Atlantic Basin, gasoil is softening. Trend-following funds cut gasoil exposure from 91% to 55% long, the lowest since 16 July, and ICE gasoil fell 4.1% in the reporting week. France plans to release 10 million barrels of diesel from reserves between November and January, and a US export ban looks less likely. US Gulf to UK Continent MR rates fell $3.2 to $8.2 per barrel.