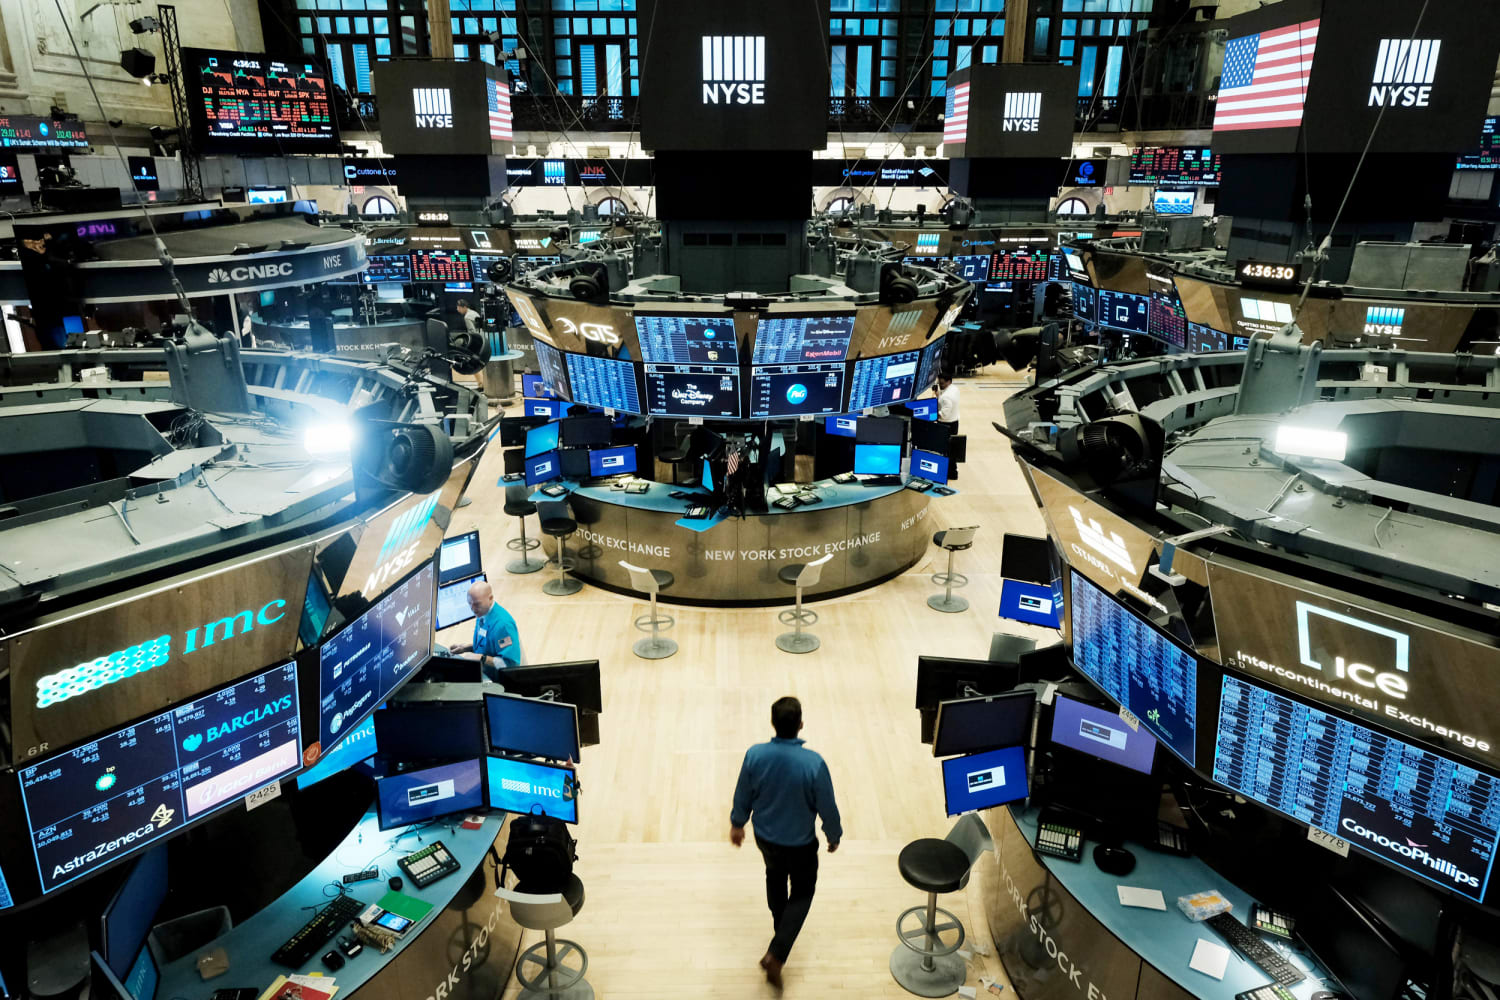
European equities fell for a second consecutive session on Tuesday as surging oil prices and anxiety over AI valuations combined to weigh on investor sentiment.
The FTSE 100 dropped 58 points, or 0.54%, to 10,706.55 by midday, with banking and technology stocks leading the decline across London’s blue-chip index.
Germany’s DAX fell 183 points, or 0.72%, to 25,137.22, while France’s CAC 40 shed 51 points, or 0.64%, to 7,817.36, extending losses for a second straight day.
The pan-European STOXX 600 fell 0.61% to 635.65, with selling pressure broad-based across industrial, mining and technology sectors throughout the morning session.
Brent crude surged above $110 a barrel to a five-month high, with futures standing at $111.52, up 1.73%, after Yemen’s Iran-aligned Houthi group said it had launched several attacks on Saudi energy, airport and military targets.
S&P 500 and Nasdaq futures pointed lower as renewed jitters over AI valuations continued to weigh on technology stocks ahead of major AI company earnings later in the week.
UK unemployment unexpectedly fell to 4.7% from 4.9% in the three months to August, according to data from the Office for National Statistics, strengthening expectations that the Bank of England could raise interest rates.
Payrolled employment increased by 13,000 in September, while regular wage growth accelerated to 3.7%, adding further weight to the case for tighter monetary policy at the Bank of England’s November meeting.
Sterling strengthened following the labour market figures, with the dollar index slipping 0.2% to 101.77 and the euro gaining 0.2% to $1.122 against the greenback.
Among individual movers, Genuit Group plunged 17% in the FTSE 250 after lowering its annual underlying operating profit forecast to approximately £84 million, well below market expectations of between £91 million and £96 million.
Anglo American led the FTSE 100 higher with a 2% gain after maintaining its annual copper production guidance despite third-quarter output falling 5% due to extreme snowfall in Chile.
The miner also reduced its copper unit-cost guidance and raised its diamond production forecast to between 25 million and 28 million carats following its acquisition of full ownership of the Gahcho Kué mine in Canada.
Bunzl was the largest blue-chip faller outside of industrial names, dropping 5% after reporting third-quarter underlying revenue growth of just 3.1% and maintaining guidance for modest growth and a broadly flat operating margin.
Ocado Group led the FTSE 250 risers with a 6% gain, extending its recent rally, while home-improvement retailer Wickes advanced 5% against the broader downward trend.
Defensive stocks provided some shelter from the wider sell-off, with Tesco gaining 1%, National Grid adding 0.7%, and Sainsbury’s advancing 0.6% as investors rotated into consumer staples and utilities.
IXICO PLC (LSE:IXI, OTC:PHYOF, FRA:PYPB) said it expects revenue to rise 28% to £8.3 million, beating its upgraded guidance after analysis orders accelerated strongly in the final quarter of the financial year.
Cornish Metals PLC (AIM:TIN) launched a proposed £135 million fundraising to advance its South Crofty tin mine in Cornwall towards first production in mid-2028, with Glencore providing backing and agreeing to buy the mine’s output for six years.
Asian markets had weakened sharply overnight, with South Korea’s Kospi dropping around 4% and Japan’s Nikkei falling approximately 1.5%, despite a partial recovery among US artificial intelligence stocks on Wall Street.
Gold traded near $4,122 an ounce, Bitcoin stood at around $81,600, and investors were also focused on UK inflation and retail sales data due later in the week as earnings season gathered pace.